Головна сторінка Державної податкової служби України
 The only state web portal
of electronic services

-
State Tax Service
of Ukraine - Contacts
The only state web portal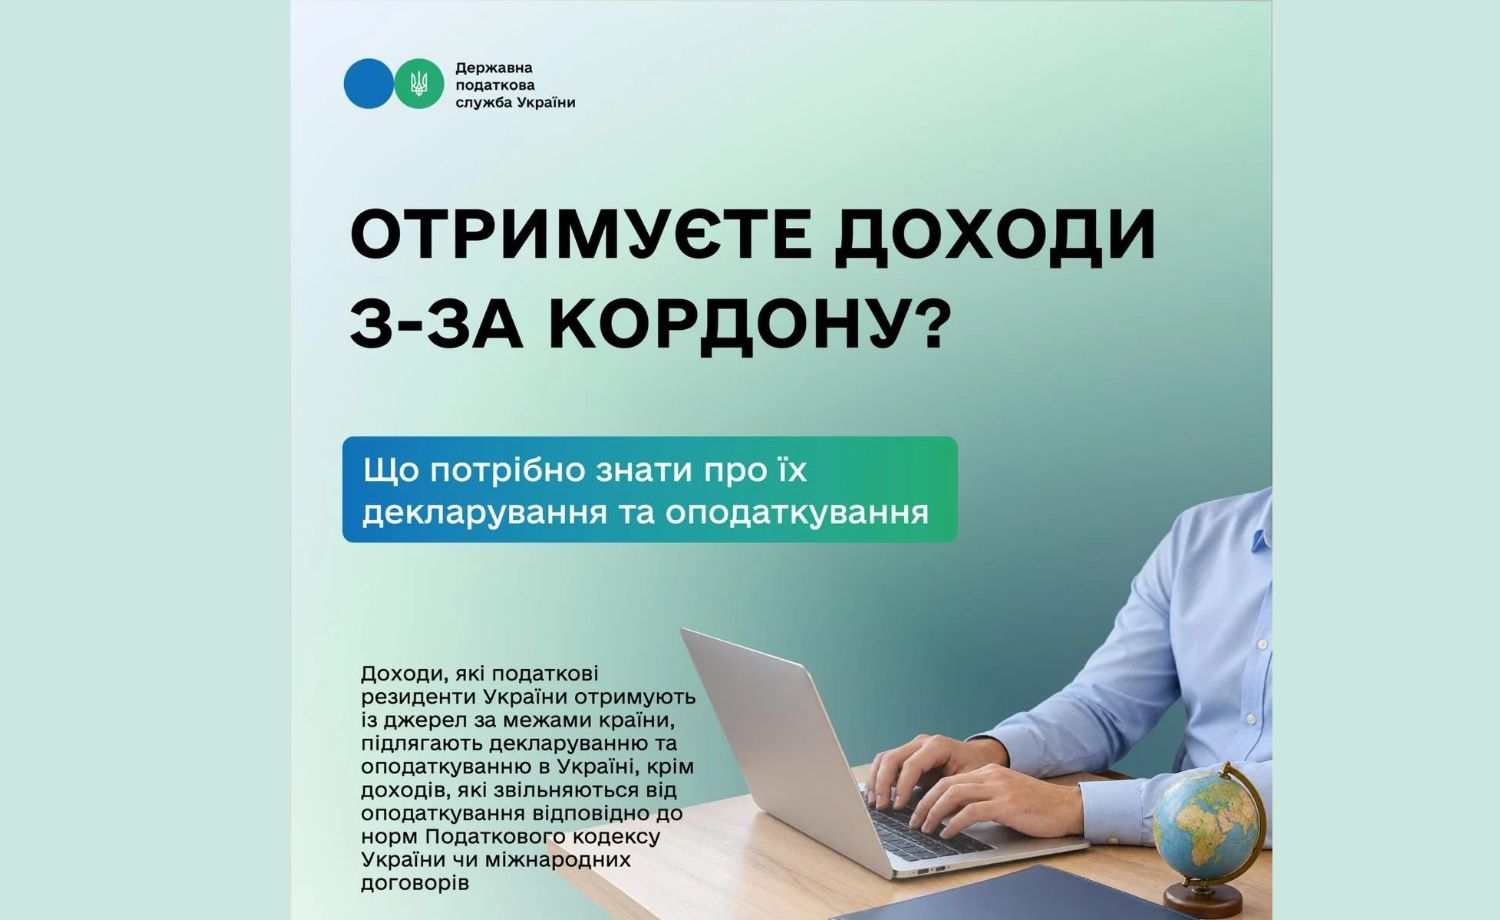
Revenues that tax residents of Ukraine receive from sources outside the country is subject to declaration and taxation in Ukraine, except for income that is exempted from taxation according to the Tax Code of Ukraine or international treaties.
Refers to any income received by residents from any activity outside the customs territory of Ukraine.
Foreign income may particularly include:
- dividends;
- interest;
- royalties;
- income from property rental;
- income from the sale of property abroad;
- inheritance and gifts;
- winnings;
- other income received outside Ukraine.
Such income is included in the total annual taxable income of individual resident of Ukraine and is subject to declaration.
What tax rates are applied?
Personal income tax on foreign income is paid at the 18% rate.
At the same time, the Tax Code of Ukraine establishes special taxation rates of certain types of income. In particular, dividends accrued by non-residents are taxed at the 9% rate.
In addition, foreign income of individuals is subject to military levy at the 5% rate.
How to avoid double taxation?
If tax has already been paid abroad on foreign income, in cases provided for by international treaties, the payer may reduce amount of the annual tax liability in Ukraine by the amount of taxes paid in another state.
To do this, submitting the annual tax declaration, it is necessary to:
- indicate amount of the tax paid abroad;
- have document confirming payment of such tax;
- take into account provisions of relevant international treaty of Ukraine on the avoidance of double taxation.
As follows, receiving income outside Ukraine does not exempt tax resident of Ukraine from the obligation to declare it. At the same time, legislation provides for the possibility of crediting taxes paid in another state in order to avoid double taxation – within limits specified by relevant international treaty.
For reference.
Taxation of the individuals’ personal income is regulated by Section IV of the Tax Code of Ukraine. Foreign income taxation procedure is determined, in particular, by Paragraph 170.11 Article 170 of the Code.
Texts of valid international treaties of Ukraine on the avoidance of double taxation are posted on the official website of the Ministry of Finance of Ukraine at the link:
https://mof.gov.ua/uk/international_agreements_of_ukraine_on_avoidance_double_taxation-543.