Головна сторінка Державної податкової служби України
 The only state web portal
of electronic services

-
State Tax Service
of Ukraine - Contacts
The only state web portal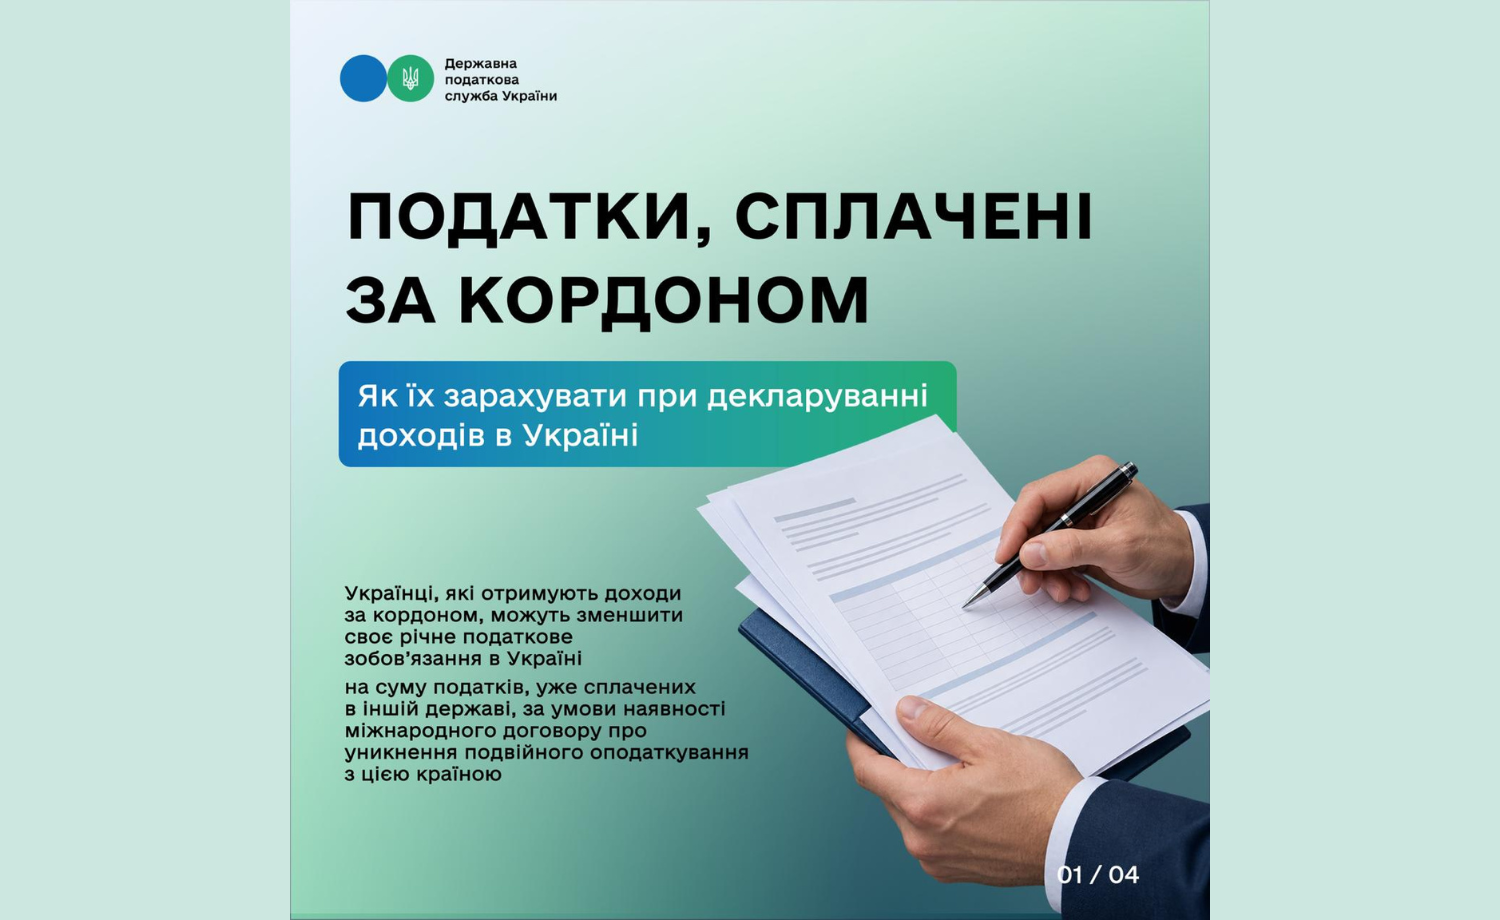
Ukrainians who receive income abroad may reduce their annual tax liability in Ukraine by the amount of taxes already paid in another country, provided that there is international agreement on the avoidance of double taxation with this country.
To do this, the payer must reflect amount of taxes paid outside Ukraine in the annual property status and income tax declaration.
Herewith, the Tax Code defines list of taxes that cannot be credited to reduce tax liability. In particular, the following are not taken into account:
- taxes on capital or capital gains;
- property taxes;
- postal taxes;
- sales taxes;
- other indirect taxes.
Amount of tax credit paid abroad cannot exceed tax on annual taxable income calculated according to Ukrainian legislation.
To exercise right to credit foreign taxes, it is necessary to obtain certificate from the competent authority of the country where income was received:
- amount of paid tax (levy);
- base and/or taxation object.
Such certificate must be legalized according to requirements of international treaties or legislation of Ukraine, unless otherwise provided for by international treaties.
State Tax Service reminds: timely declaration of foreign income and proper confirmation of taxes paid abroad will help avoid double taxation and correctly fulfill tax obligations.
For reference.
Taxation of personal income is regulated by Section IV of the Tax Code of Ukraine. Foreign income taxation procedure is particularly determined by Paragraph 170.11 Article 170 of the Code.
Texts of valid international treaties of Ukraine on the avoidance of double taxation are posted on the official website of the Ministry of Finance of Ukraine at the link:
https://mof.gov.ua/uk/international_agreements_of_ukraine_on_avoidance_double_taxation-543.