Головна сторінка Державної податкової служби України
 The only state web portal
of electronic services

-
State Tax Service
of Ukraine - Contacts
The only state web portal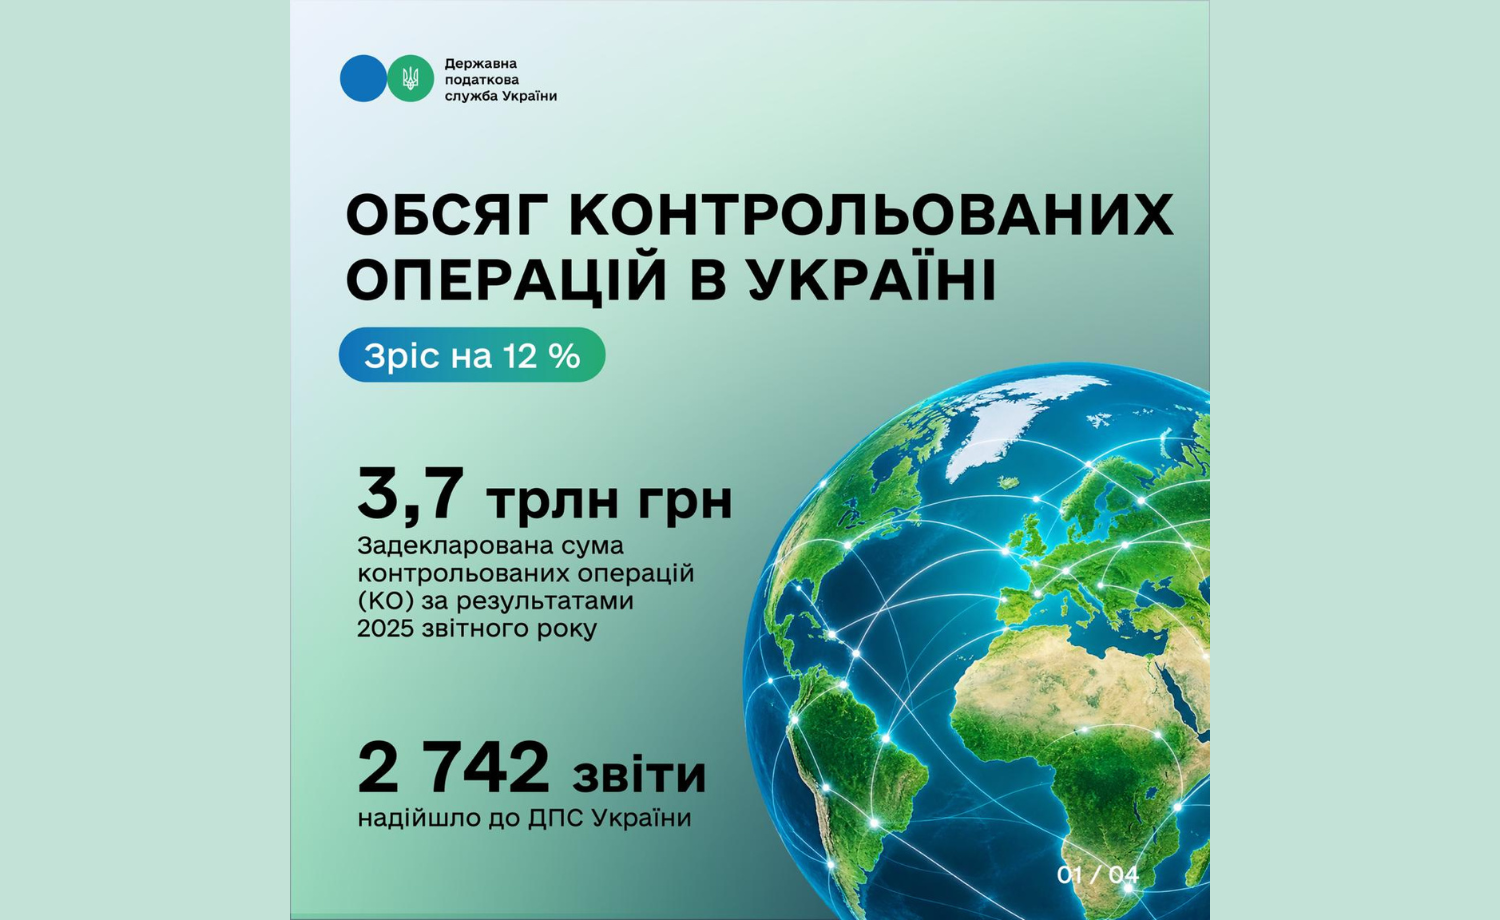
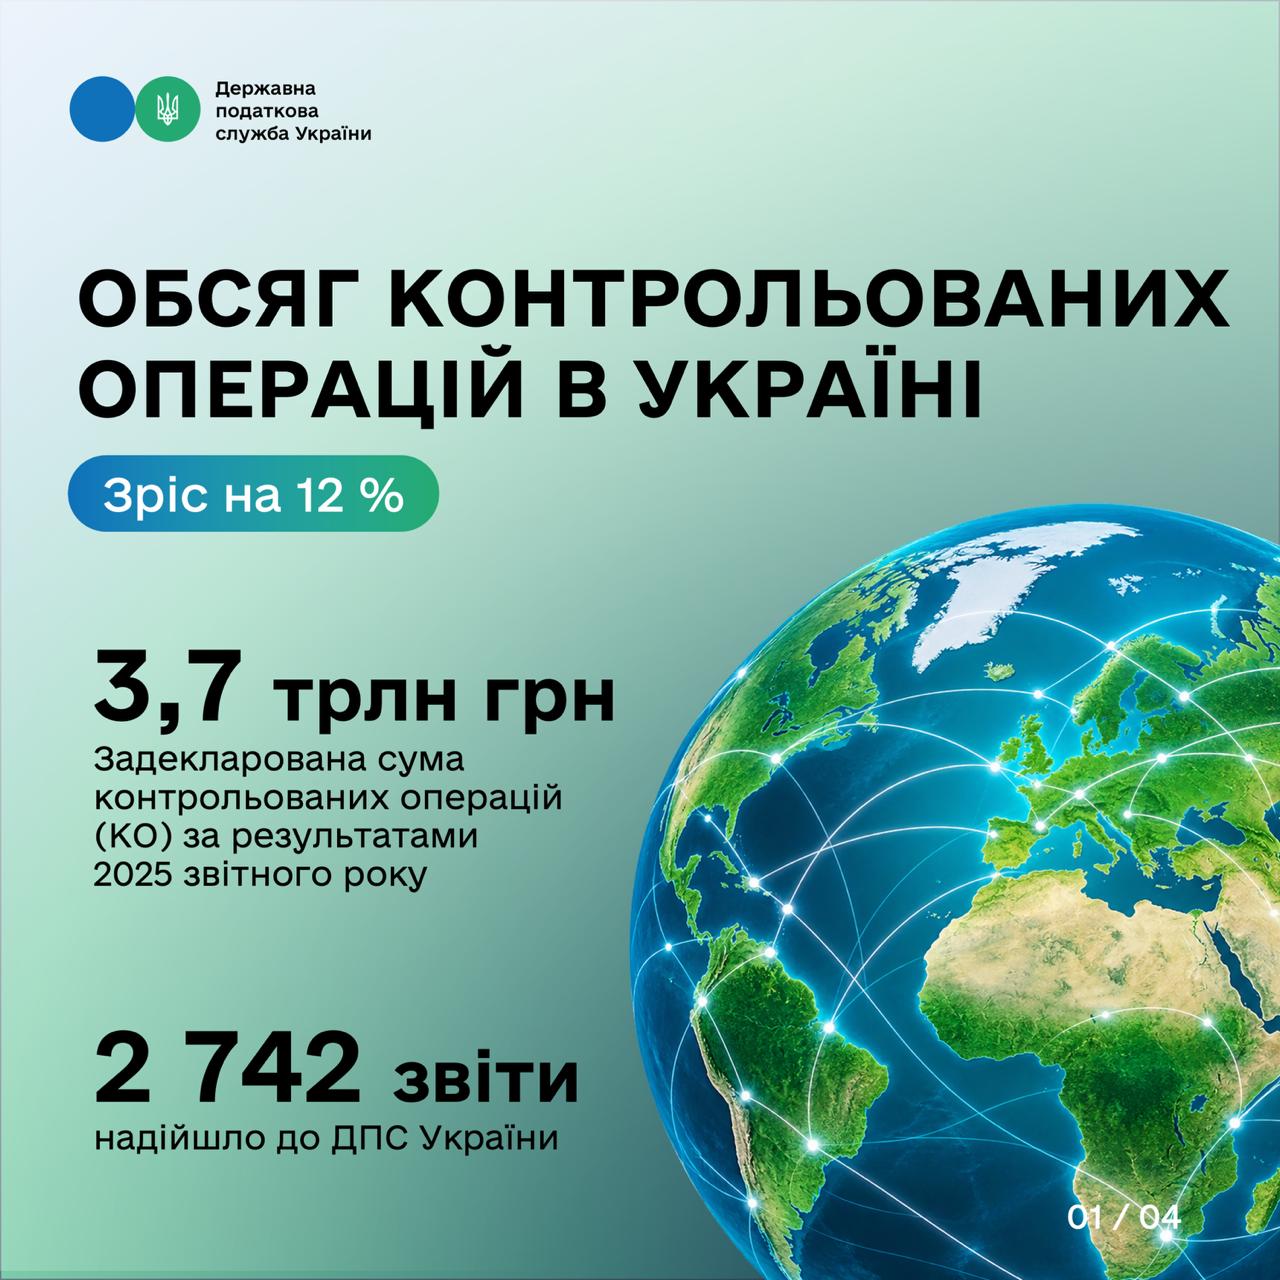
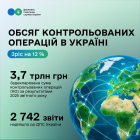
According to results of the reporting year2025, the State Tax Service of Ukraine received 2 742 reports on controlled transactions. This is approximately 2% less than the last year’s figure. At the same time, amount of controlled transactions declared by the taxpayers increased by 12% and reached 3.7 trillion UAH.
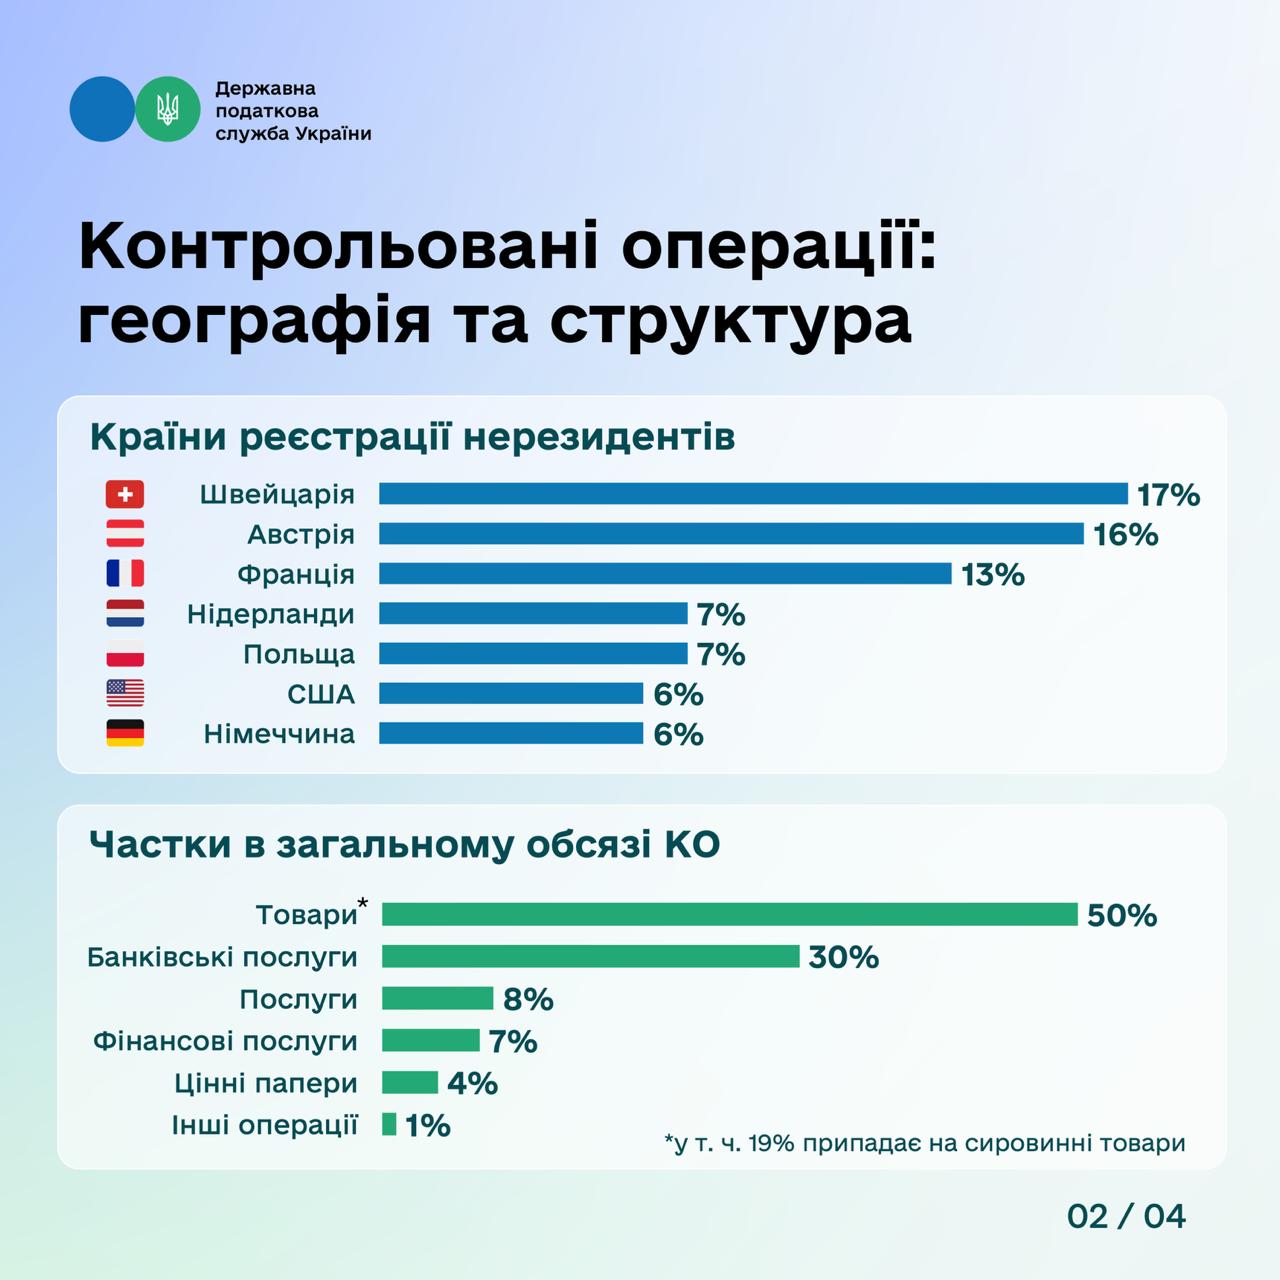
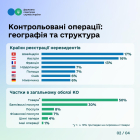
The biggest share of controlled transactions was carried out with non-residents registered in the Swiss Confederation (17%), Republic of Austria (16%), French Republic (13%), Kingdom of the Netherlands, Republic of Poland (7% each), United States of America and Federal Republic of Germany (6% each).
In the total volume of controlled transactions, transactions with products prevail – 50% (including 19% for raw materials). Another 30% are banking services. Shares of other categories are distributed as follows: services – 8%, financial services – 7%, securities transactions – 4%, other transactions – 1%. To establish compliance of controlled transactions’ conditions with the "arm's length" principle, payers most often used the following methods:
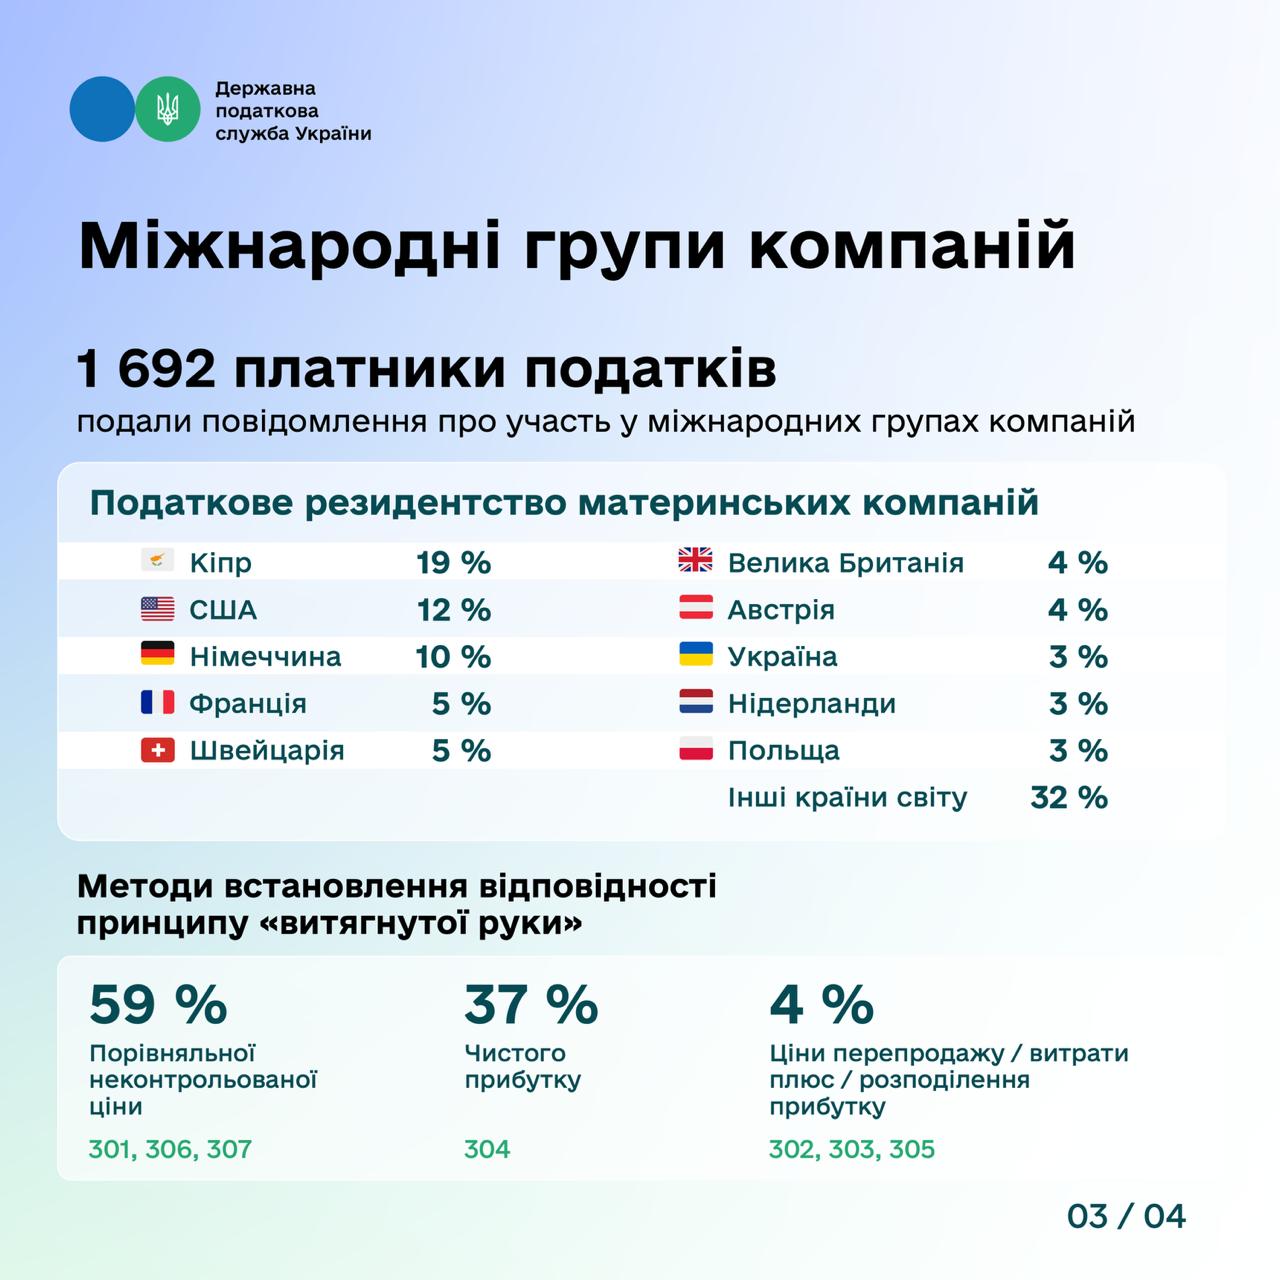
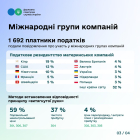
- comparative uncontrolled price (301, 306, 307) – 59%,
- net profit (304) – 37%,
- resale cost/costs plus/profit distribution (302, 303, 305) – 4%.
In addition, 1 692 taxpayers submitted notifications about participation in the international groups of companies. The biggest share of parent companies of such groups are tax residents of the Republic of Cyprus – 19%, United States of America – 12%, Federal Republic of Germany – 10%, French Republic and Swiss Confederation – 5% each, United Kingdom and the Republic of Austria – 4% each, Ukraine, Kingdom of Netherlands, Republic of Poland – 3% each. Combined share of other countries of the world is 32%.
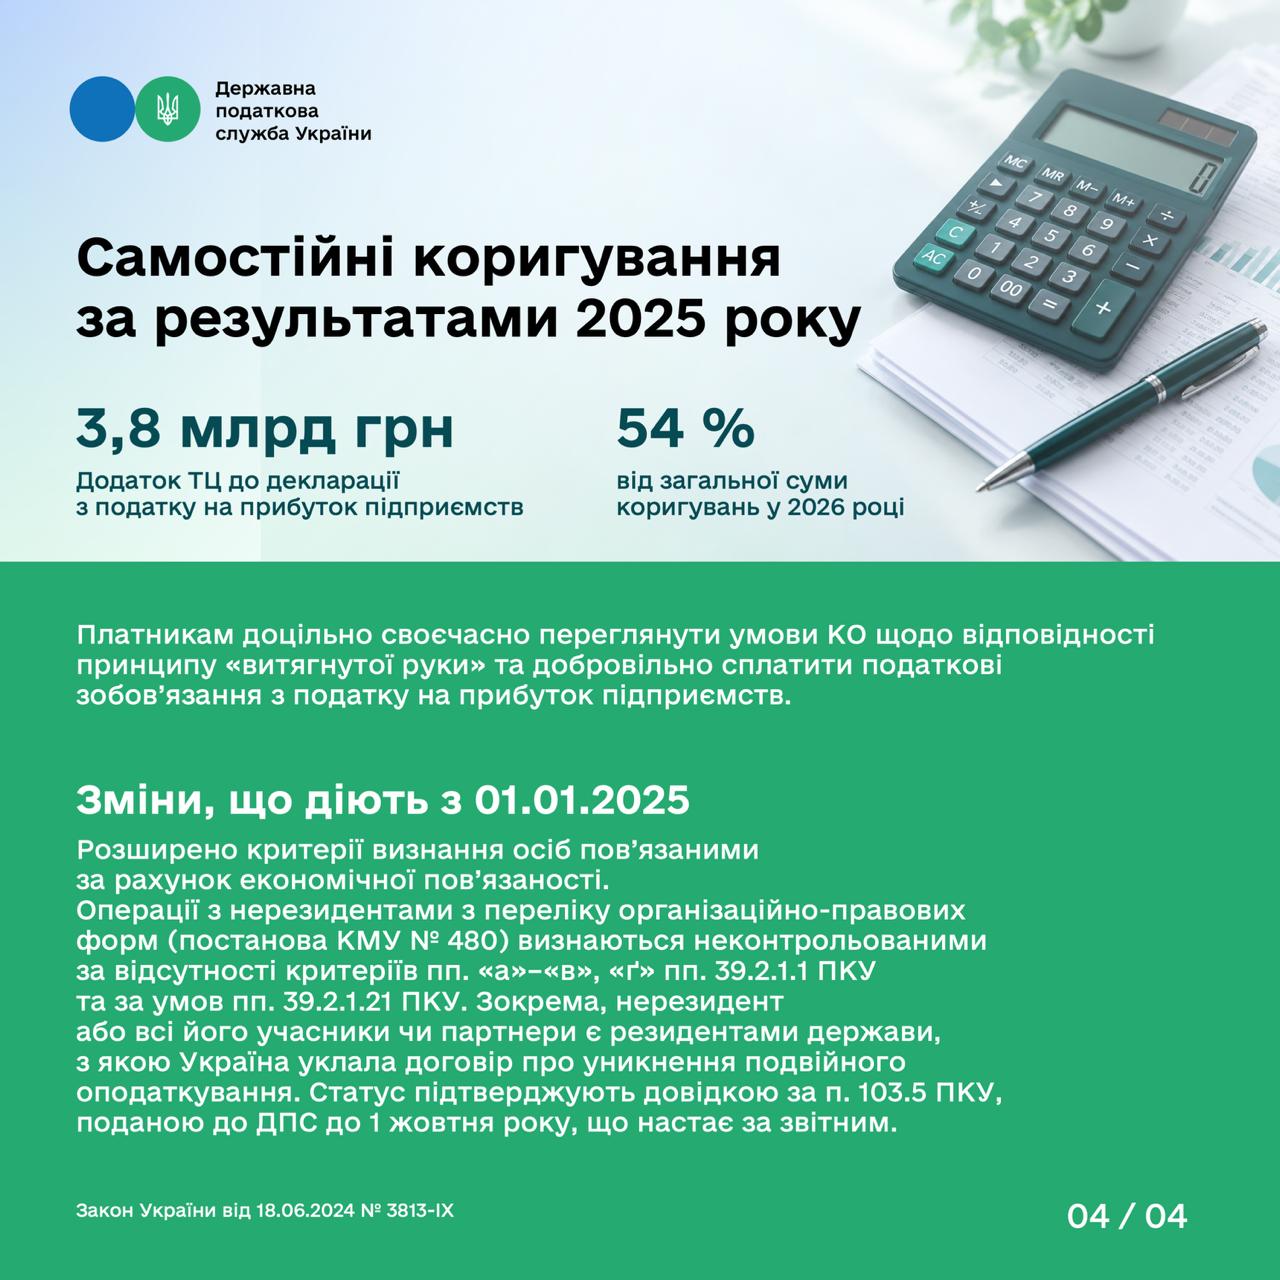
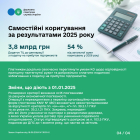
Also, payers made independent adjustments to price of controlled transactions and amounts of tax liabilities. According to results of 2025, the transfer pricing annex was submitted to the corporate income tax declaration in the amount of 3.8 billion UAH. This is 54% of the total amount of adjustments made in 2026.
Please note the advisability of timely review by payers of conditions of controlled transactions regarding their compliance with the “arm's length” principle and voluntary payment of corporate income tax liabilities before the start of transfer pricing audits.
For reference
By the Law of Ukraine № 3813-IX as of 18.06.2024 “On amendments to the Tax Code of Ukraine regarding the tax administration peculiarities during the martial law for taxpayers with a high level of voluntary compliance with tax legislation”, Sub-paragraph 39.2.1 Paragraph 39.2 Article 39 of the Code was added with Sub-paragraph 39.2.1.21, provisions of which entered into force on 01.01.2025. According to the specified norm, business transactions of the taxpayer with a non-resident, whose organizational and legal form is included in the list of organizational and legal forms of non-residents (Resolution of the Cabinet of Ministers of Ukraine № 480 as of 04.07.2017), in the absence of criteria specified in Sub-paragraphs "a" - "c", "g" of Sub-paragraph 39.2.1.1 of the Code, are recognized as uncontrolled provided, in particular, that the non-resident (or all its participants or partners) are residents of the state (territory) with which Ukraine has concluded international agreement on the avoidance of double taxation. This status is confirmed by submitting to the central executive body implementing state tax policy, by October 1 of year following the reporting year, a certificate according to Paragraph 103.5 Article 103 of the Code.
Law of Ukraine № 3813-IX as of 18.06.2024 “On amendments to the Tax Code of Ukraine regarding the tax administration peculiarities during the martial law for the taxpayers with a high level of voluntary compliance with tax legislation” from 01.01.2025 expanded criteria for recognizing persons as related due to the so-called economic connection.