Головна сторінка Державної податкової служби України
 The only state web portal
of electronic services

-
State Tax Service
of Ukraine - Contacts
The only state web portal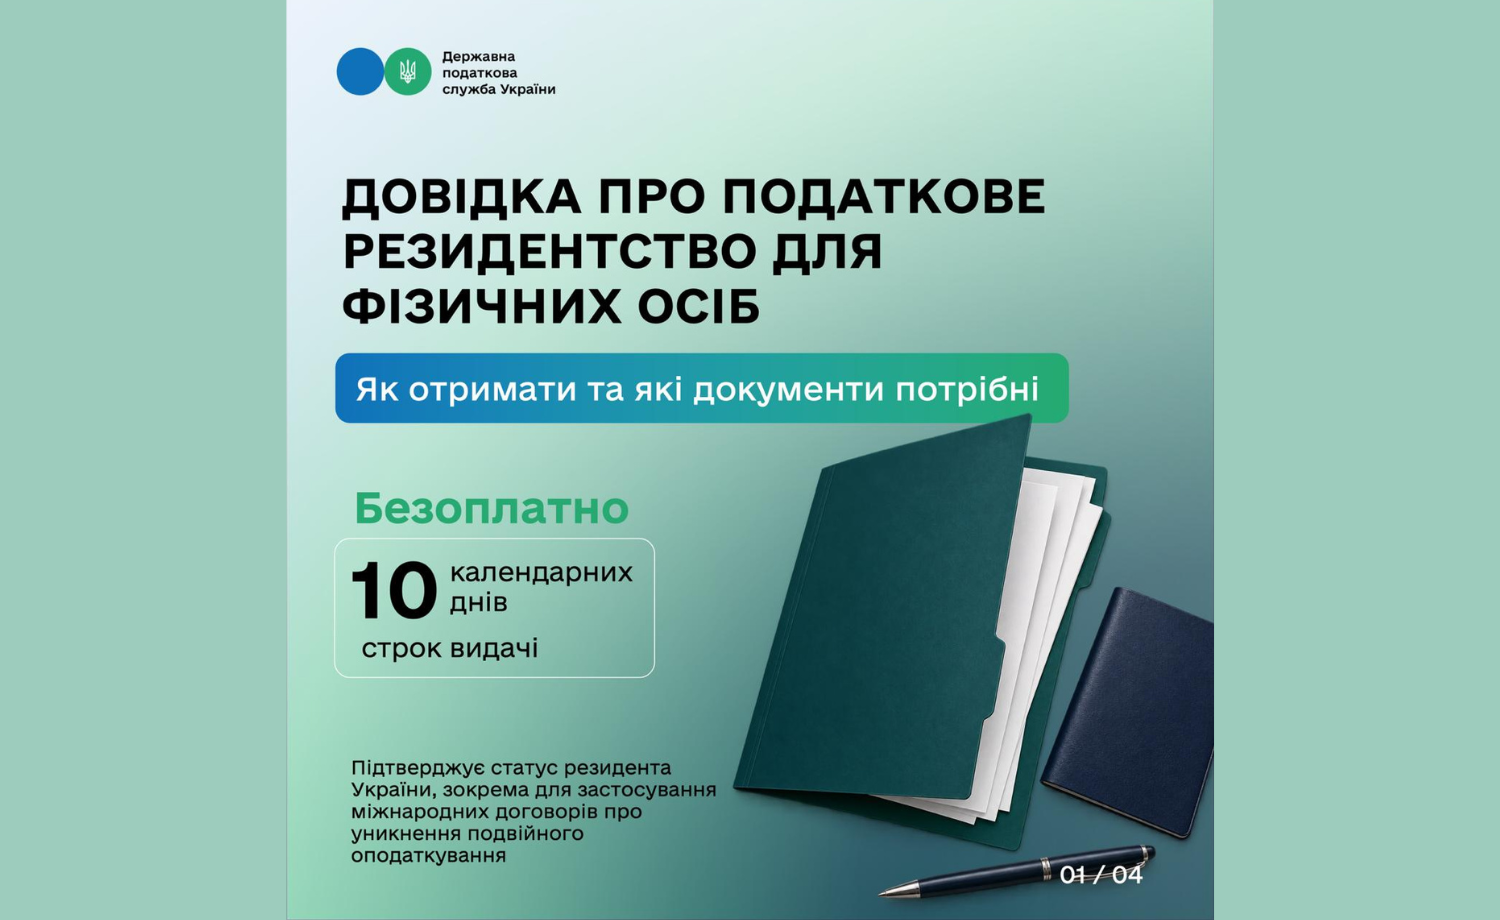
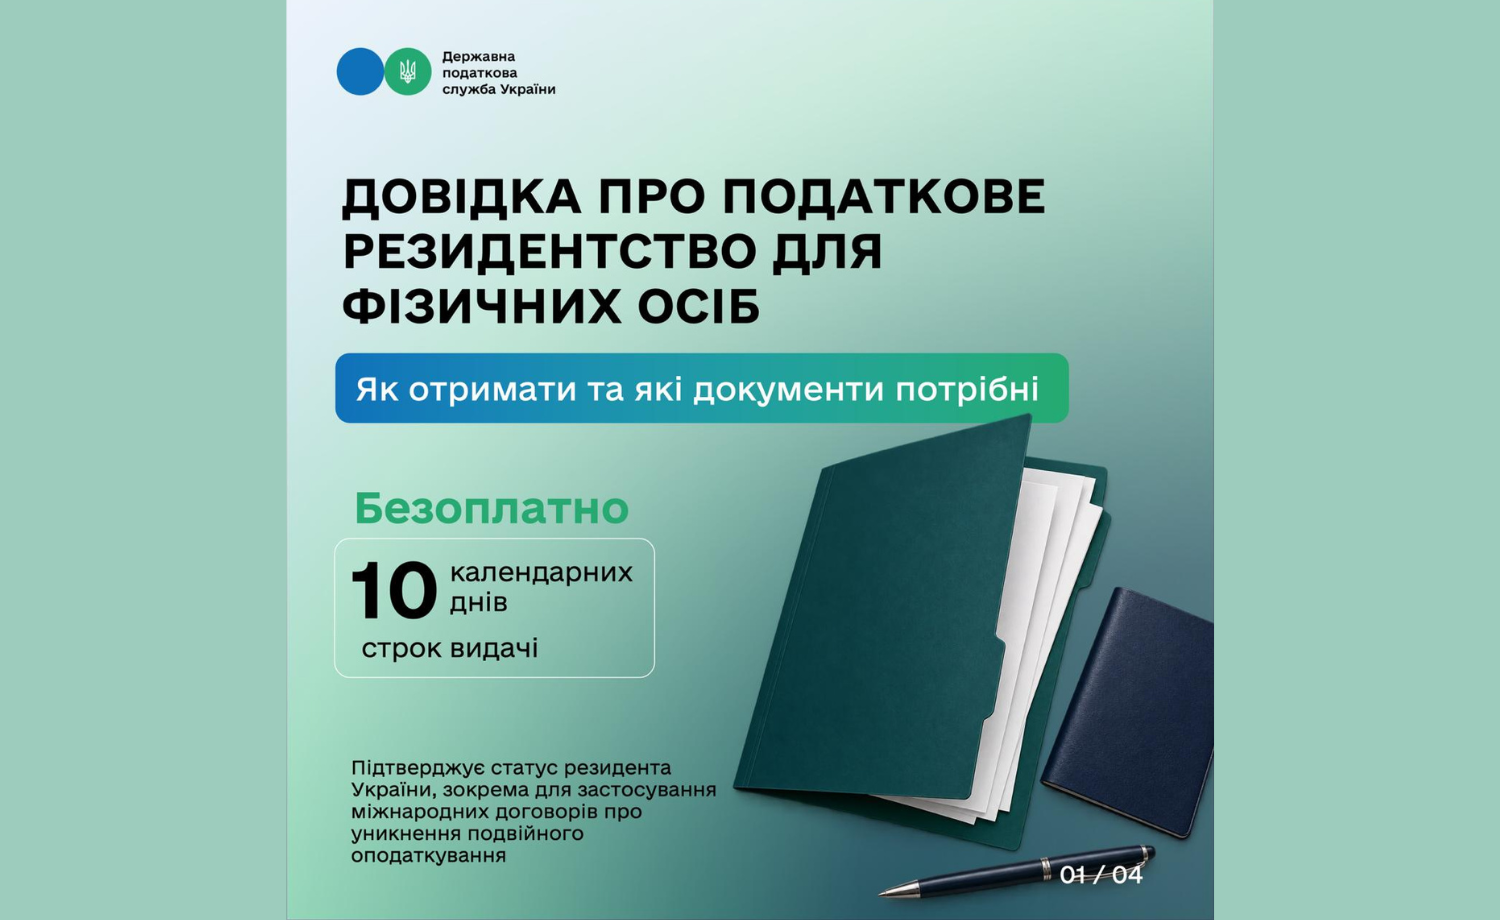
Individuals – taxpayers can obtain certificate of tax resident status in Ukraine to confirm their resident status, in particular for application of provisions of the international treaties on the avoidance of double taxation.
Service is free of charge and certificate is issued within 10 calendar days.
How to order certificate
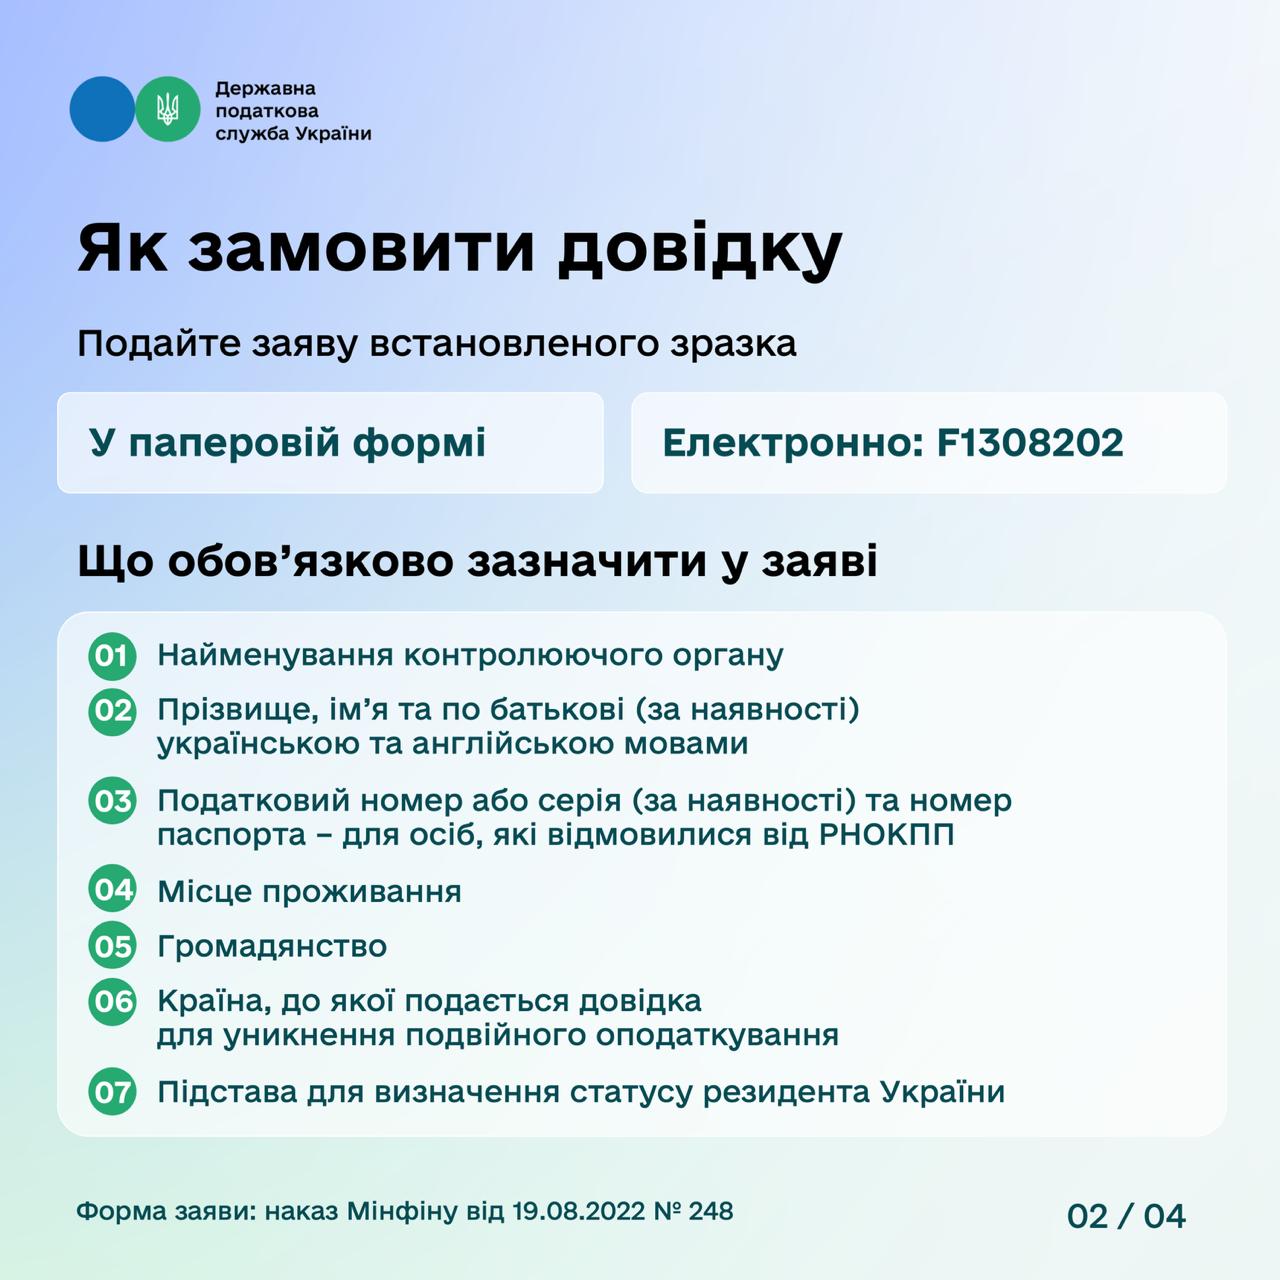
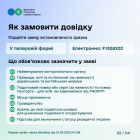
To obtain certificate, it is necessary to submit application of the established form, approved by Order of the Ministry of Finance of Ukraine № 248 as of 19.08.2022.
Application can be submitted:
- in paper form;
- in electronic form – using F1308202 form.
What must be indicated in the Application?
- title of the controlling authority to which application is submitted;
- surname, first name and patronymic (if any) in Ukrainian and English;
- tax number / series (if any) and passport number (for persons who refused the registration number of the taxpayer’s account card);
- residence place;
- citizenship;
- name of the country to which certificate will be submitted for the avoidance of double taxation;
- basis for determining status of a resident of Ukraine.
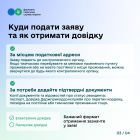
Where to submit application
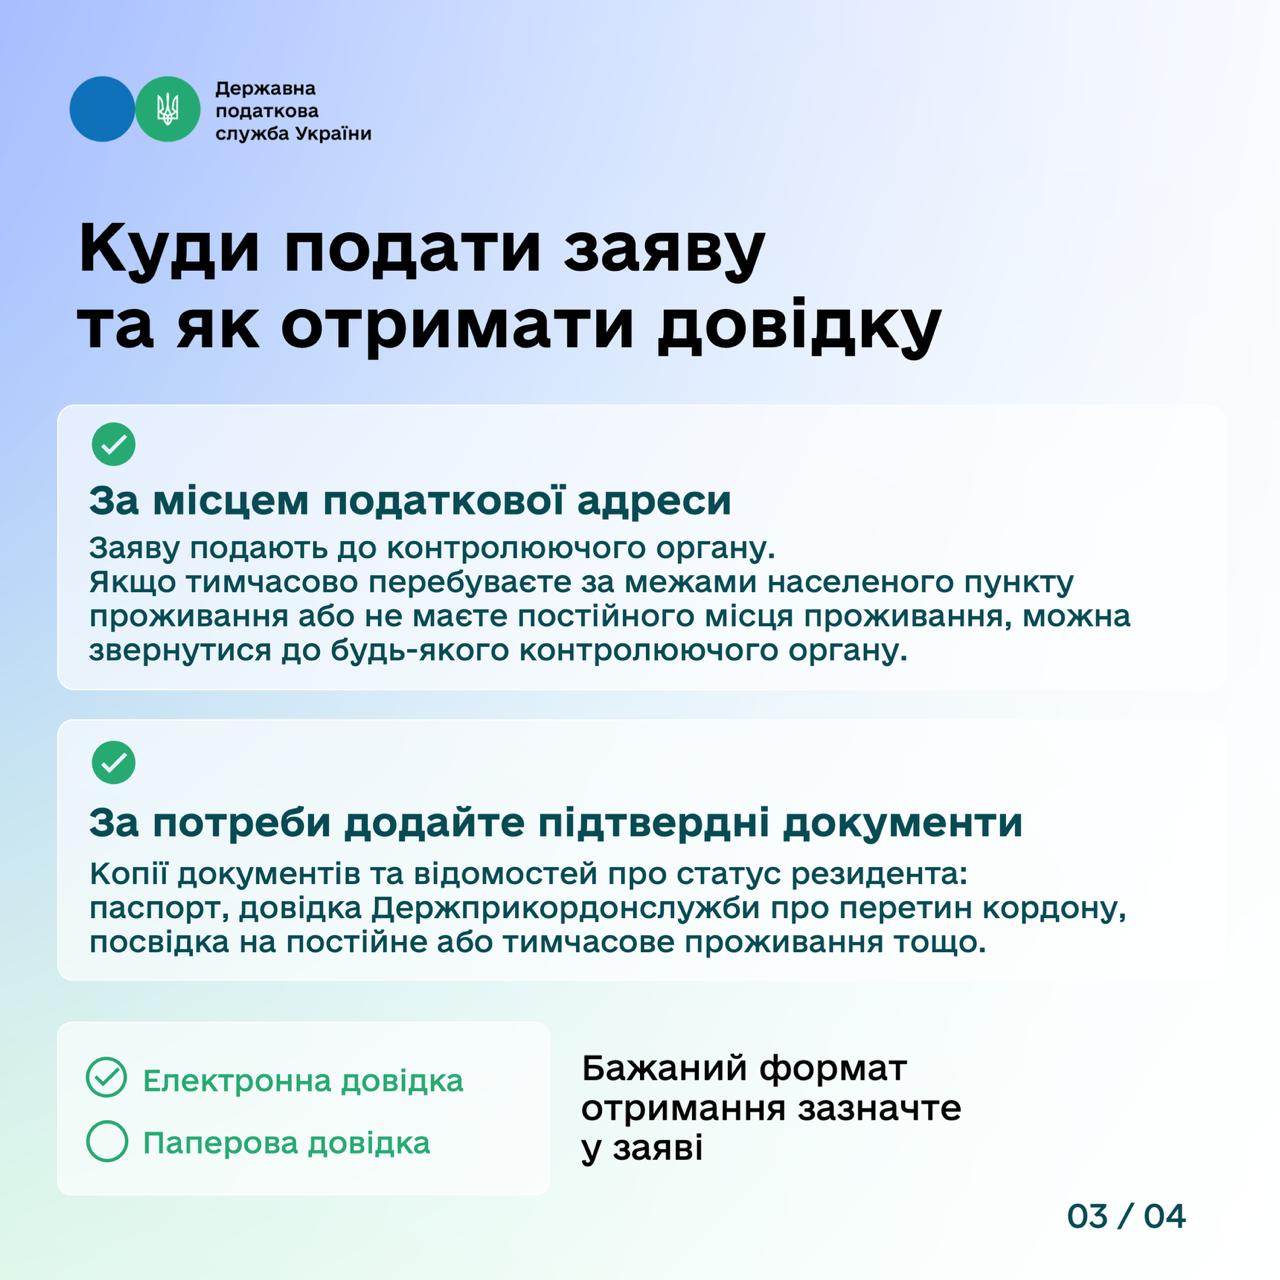
Application is submitted to the controlling authority at the place of tax address.
At the same time, individuals who are temporarily outside the residence settlement or do not have permanent residence place can apply to any controlling authority.
If necessary, copies of documents and information confirming status of the tax resident can be added to application. For example, this may be copy of a passport, certificate from the State Border Service about crossing the border, permanent or temporary residence permit, etc.
How to get ready-made certificate
Certificate can be received in paper or electronic form. Preferred format for receipt must be indicated in the application.
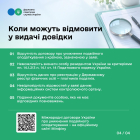
When issuance of certificate may be refused
Grounds for refusal may be:
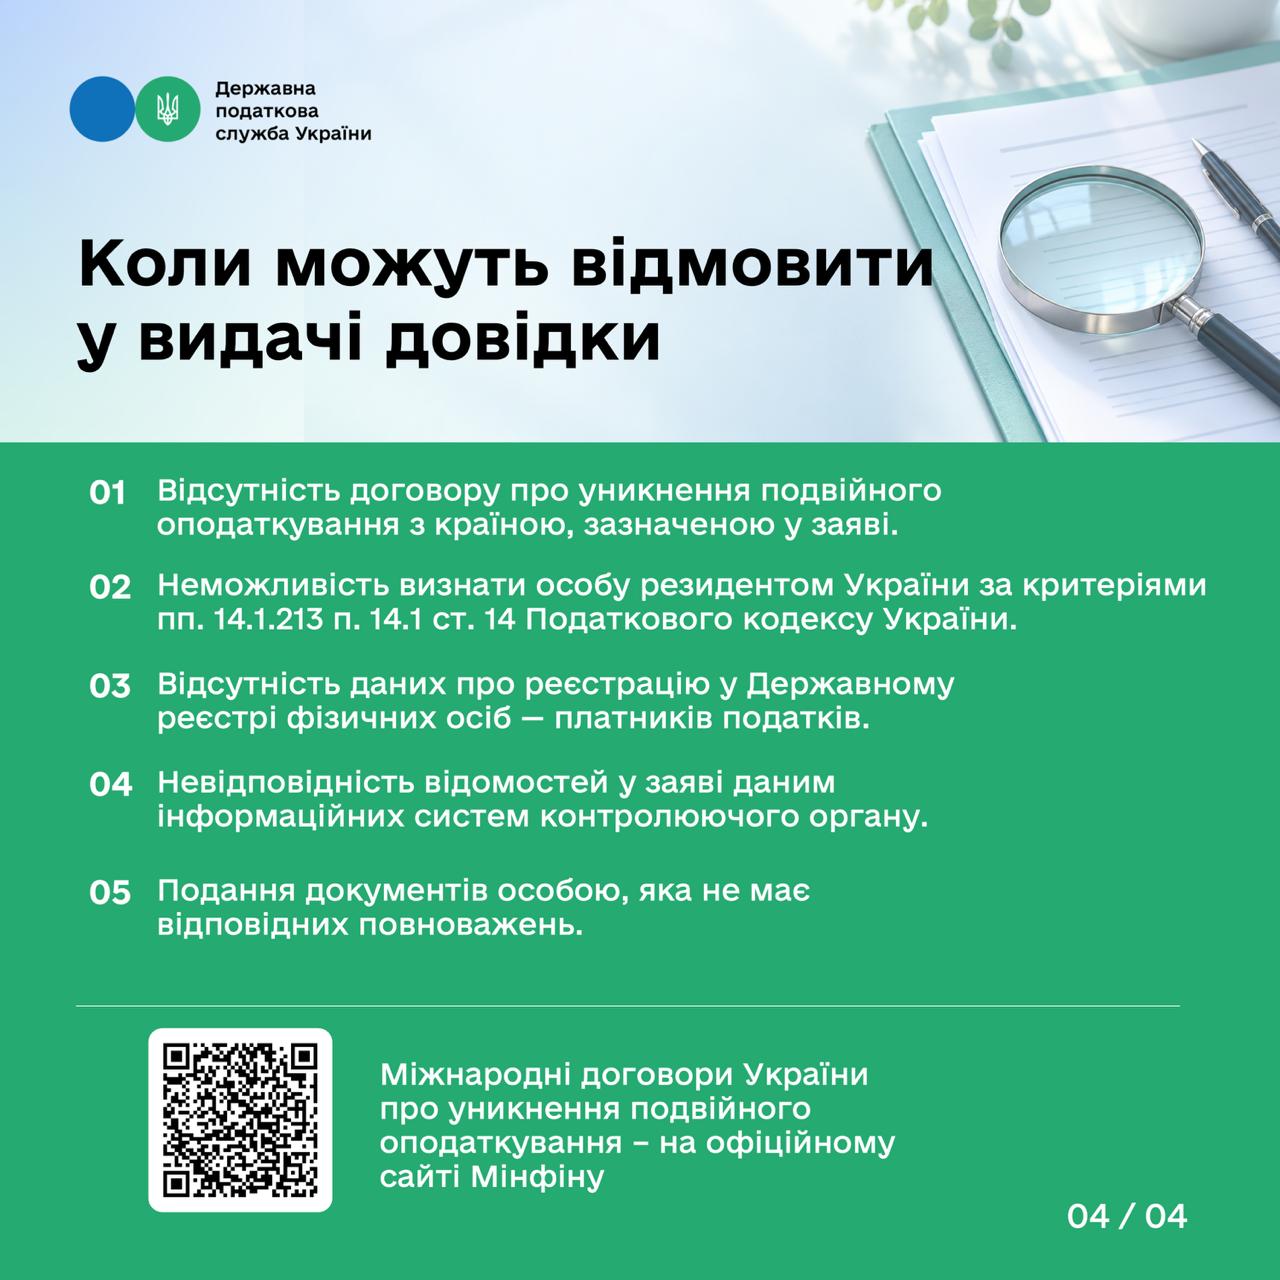
- absence of the double taxation treaty with country specified in the application;
- impossibility of recognizing person as a resident of Ukraine according to criteria specified in Sub-paragraph 14.1.213 Paragraph 14.1 Article 14 of the Tax Code of Ukraine;
- absence of data on the registration of individual in the State Register of Individuals – Taxpayers;
- inconsistency of information specified in the application with data of information systems of the controlling authority;
- submission of documents by individual who does not have appropriate authority.
For reference.
Texts of Ukraine’s current international treaties on the avoidance of double taxation are posted on the official website of the Ministry of Finance of Ukraine at the link:
https://mof.gov.ua/uk/international_agreements_of_ukraine_on_avoidance_double_taxation-543.